Buying a Home in a Charleston Flood Zone: Buyer's Guide
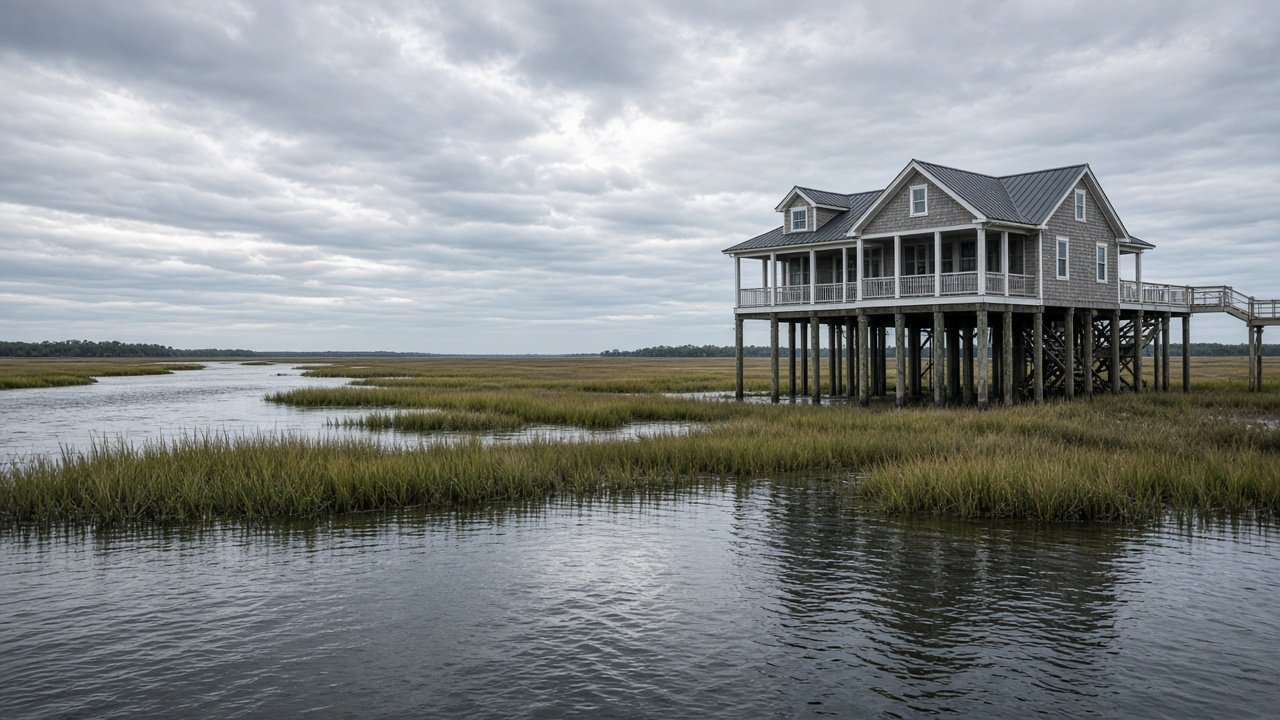
Yes, you can buy a home in a Charleston flood zone, but plan ahead. If the home is in a FEMA high-risk zone and you use a typical mortgage, your lender will require flood insurance. Before you make an offer, check the flood map, get an insurance quote, and ask about the home’s flood history.
Key Takeaways
- Homes in FEMA Special Flood Hazard Areas (zones starting with A or V) need flood insurance for most mortgages.
- Look up any address on FEMA’s Flood Map Service Center.
- NFIP coverage goes up to $250,000 for the building and $100,000 for contents (FloodSmart).
- Charleston Harbor had 52 tidal flood events in 2025, two of them major (Post and Courier).
- Get a flood insurance quote before your inspection period ends.
Why Does Flooding Matter So Much in Charleston?
Charleston is a low-lying city surrounded by rivers, creeks, and marsh. That’s a big part of its beauty, and a big part of its flood risk.
The Post and Courier’s Rising Waters Lab reported that Charleston Harbor saw 52 tidal flood events in 2025, about one per week. Two were “major,” 12 were “moderate,” and the rest were “minor.” October 2025 alone had 18 events, tying October 2019 for the second-highest month on record.
The National Weather Service uses the Cooper River tide gauge to measure these events:
- Minor flooding: starts at 7.0 feet
- Moderate flooding: starts at 7.5 feet
- Major flooding: starts at 8.0 feet
Many of the biggest events happen during king tides, the extra-high tides that come a few times a year. The City of Charleston has a king tides page with tips for residents.
What Is a FEMA Flood Zone?
A flood zone is an area FEMA maps by flood risk. The key terms:
- Special Flood Hazard Area (SFHA): A high-risk area with at least a 1% chance of flooding in any year. These zones start with A or V.
- V zones: Coastal areas that also face wave action. Building rules are stricter.
- Zone X: Moderate-to-low risk. Flood insurance isn’t required, but floods still happen.
- Base Flood Elevation (BFE): The height floodwater is expected to reach in a 1%-chance flood.
- Elevation Certificate: A document showing how high a home sits compared with the BFE. It can affect your insurance cost.
When Is Flood Insurance Required?
Under federal law, lenders must require flood insurance on homes in a mapped high-risk flood area when the loan is federally regulated or federally backed. That covers most conventional, FHA, VA, and USDA loans.
Good news on timing: NFIP policies usually take 30 days to kick in, but there’s no waiting period when you buy the policy while getting a mortgage, as long as you apply and pay at or before closing (FloodSmart).
Should I Buy Flood Insurance If It’s Not Required?
Often, yes. Standard homeowners insurance usually doesn’t cover flood damage. Heavy rain and storm surge don’t stop at a map line. Policies outside high-risk zones also tend to cost less.
How Do I Check a Charleston Home’s Flood Risk Before I Buy?
- Look up the flood zone on FEMA’s map.
- Ask for an Elevation Certificate if the seller has one.
- Get a flood insurance quote early, from the NFIP and a private insurer if possible.
- Read the seller’s disclosure and ask directly about past flooding and insurance claims.
- Drive by at high tide, especially during a king tide, and after a heavy rain.
- Look at the home’s height. Raised homes on pilings or high foundations often have lower risk.
A Little Lowcountry Storm History
On the night of September 21-22, 1989, Hurricane Hugo made landfall near Charleston as a Category 4 storm. Its storm surge reshaped the coast and led to stronger building codes in South Carolina. Many raised homes you see on the islands today reflect lessons learned from storms like Hugo.
How Does Flood Insurance Affect My Mortgage?
Your flood premium is part of your monthly housing payment, often paid through escrow. Lenders count it when figuring what you can afford. A pricey flood policy can shrink your budget, which is why we recommend a quote before you’re under contract.
Coastal Funding Corporation can help you compare conventional, FHA, VA, USDA, and jumbo options with your full payment in view. For the bigger market picture, see our Charleston housing market report. Shopping downtown? Read Buying a Historic Home in Charleston.
Frequently Asked Questions
Do I need flood insurance to buy a home in Charleston?
If the home is in a FEMA Special Flood Hazard Area (zones starting with A or V) and you use a federally regulated or federally backed mortgage, your lender will require flood insurance. Outside those zones it’s optional but often wise.
How do I find a home’s flood zone?
Search the address on FEMA’s Flood Map Service Center at msc.fema.gov. Your lender will also order a flood zone determination during the loan process.
How much flood insurance can I get through the NFIP?
The National Flood Insurance Program offers up to $250,000 of building coverage and up to $100,000 of contents coverage for a home. Private flood policies may offer higher limits.
Is there a waiting period for flood insurance when buying a home?
Normally NFIP policies take effect after 30 days, but there’s no wait when you buy the policy in connection with getting a mortgage, as long as you apply and pay by closing.
How often does Charleston flood from high tides?
Charleston Harbor had 52 tidal flood events in 2025, including two major floods, according to the Post and Courier’s review of National Weather Service data.
Buying Near the Water? Let’s Plan It Right.
We’ll help you see the full payment, flood insurance included. Call Coastal Funding Corporation at (843) 212-6200 or visit www.charlestonmtg.com to talk with a licensed loan officer.
About Coastal Funding Corporation in Charleston
Coastal Funding Corporation (NMLS 103035) is a mortgage broker helping Charleston and Lowcountry buyers compare loan options from multiple wholesale lenders. We help with purchases and refinances using conventional, FHA, VA, USDA, and jumbo loans, plus DSCR loans for investment properties. This article was written by our team and reviewed for accuracy as of the date shown.
Coastal Funding Corporation | NMLS 103035 | (843) 212-6200 | www.charlestonmtg.com. Equal Housing Opportunity. This is not a commitment to lend. All loans are subject to credit approval, underwriting guidelines, and property eligibility. Rates, terms, and programs are subject to change without notice. Market and rate figures cited are third-party data as of the dates shown and are not quotes or offers from Coastal Funding Corporation. Verify our license at NMLS Consumer Access.